PharmaLectures.com

Courses › Pharma export and key account management › Getting paid by Europeans: payment terms, letters of credit and credit insurance

Getting paid by Europeans: payment terms, letters of credit and credit insurance

Get European invoices paid on time by fixing terms before the contract is signed.

A letter of credit is a bank's written promise to pay an exporter once the exporter presents documents that comply with the credit's terms, such as the invoice, transport document and certificate of analysis. Most letters of credit follow the International Chamber of Commerce rules known as UCP 600, under which banks deal with documents, not goods, and a credit is irrevocable. For pharma exporters selling to Europe, it is one of several ways to get paid, alongside open account terms and trade credit insurance. This course shows when each one fits.

  • 6 audio modulesthree lengths each
  • 1 h to 5 hbriefing to expanded
  • Workbook, transcript, certificateand a recorded quiz per module
  • Finance, saleswho it is written for

Why letter of credit training matters

A large distributor stops paying. Sales holds the next shipment, and finance spends days finding out which local collection rules apply. The quarter closes with the invoice still open and a buyer who now answers every call with care.

What changes after this course

Your sales and finance teams agree payment terms, documents and cover before signing, and they spot a risky clause while it can still be changed. You hold a certificate per learner and a training record for every person, ready for your files.

Watch the pitch

3:43 on how an audio course is bought, listened to and recorded. Full screen, one click.

Watch the pitch3:43, full screen, one click

Letter of credit training: what this course gives your people

Your sales manager answers a distributor's push for ninety-day terms on the call, not after a week with legal. They know the Late Payment Directive, 2011/7/EU, sets sixty days as the limit unless the contract expressly agrees longer and the term is not grossly unfair. They quote statutory interest from the first day late, and finance knows what to expect in each market before the first pallet leaves.

Export operations checks the draft Letter of Credit against the Uniform Customs and Practice for Documentary Credits, UCP 600, before sales accepts it. A wrong consignee name or a shipment date past the latest allowed one gets fixed by amendment while that is still easy, not found when the bank examines the documents under Article 14. Incoterms 2020 and payment milestones are chosen together, so risk and money move at the same point.

Finance directors put two credit insurance policies side by side and say which one fits the buyers and countries in the portfolio, and which limits would stop a claim. They can tell the board when a Letter of Credit is the better shield and when cover is. Commercial risk and political risk are judged as separate decisions, not one line in a quote.

When a distributor goes quiet, your credit controller follows a written ladder: reminder, statutory interest claim, formal demand, then the right court or mediation route. They know the European Payment Order, Regulation 1896/2006, exists for uncontested claims, and that mediation under Directive 2008/52/EC can keep the buyer ordering. Outside counsel receives a prepared file, not a blank page.
Who needs letter of credit training

  • International Sales Manager

    A distributor offers to sign today if you accept ninety-day terms. You need the wording that keeps the deal alive and the exposure written down, before the call ends.

  • Credit Controller

    A large distributor ignores the third reminder. You need to know which legal route fits the country and how to escalate without ending the relationship.

  • Finance Director

    The board asks how safe your European receivables are. You decide between a Letter of Credit and trade credit insurance for each market, and you can explain the choice.

  • Export Operations Specialist

    The issuing bank refuses your documents over a mismatch in a date or a description. You want the file right on first presentation, with the credit checked before shipment.

Roles: Business development and export sales, Finance, pricing and tenders

Businesses: every kind of pharma company

Countries: India, China, Türkiye, Korea, Japan, Taiwan, Egypt, Gulf and MENA, Brazil and Latin America, Pakistan, Bangladesh and Vietnam, United States, Europe

Selling into: Europe and the UK

Courses are in English. Other languages on request.

After this course your people can

  1. Calculate statutory interest on an overdue European invoice under the Late Payment Directive 2011/7/EU.
  2. Choose the Incoterms 2020 rule that fits a temperature-sensitive pharmaceutical shipment and set payment milestones to match.
  3. Check a draft Letter of Credit against UCP 600 and list the amendments to request before shipment.
  4. Compare two trade credit insurance policies on commercial risk, political risk and the limits that block claims.
  5. Run a written escalation from first reminder to formal demand, European Payment Order or mediation.
  6. Score a new European customer on a creditworthiness checklist before the first order is accepted.

What the company gets

  • Payment terms in European contracts are set by finance and sales together, so every exception to the sixty-day limit is written down and agreed.
  • Fewer shipments sit waiting because a bank found a discrepancy in the documents, so cash arrives when the sale says it should.
  • Credit insurance is bought against the markets you actually sell in, and the board can see why each policy was chosen.
  • An overdue invoice triggers a known sequence of steps, so the first call to outside counsel comes with a complete file.

The evidence: questionnaire, training record, certificate

EU GMP Chapter 2, section 2.11, and 21 CFR 211.25 both ask for training that is documented and shown to work. This is what each learner leaves behind.

A recorded questionnaire per module

Every one of the 6 modules ends with a multiple-choice questionnaire. The result is recorded per person with a timestamp, whichever of the three lengths the person listened to.

A per-person training record

The export lists each learner, each module, the result and the date, which is the training record EU GMP Chapter 2 and 21 CFR 211.25 ask you to keep and the first thing an inspector asks for.

A certificate per learner

Name, company, course, hours, the guideline version taught and the date. It documents in-company training; it is not a professional qualification or an accreditation.

Your pass mark, your rule

There is no fixed pass mark. Your quality or human-resources manager decides what counts as passed and when a module is retaken, exactly as your training procedure says.

Delivered within 72 hours of payment, with the workbook, the full transcript and a source for every fact in the audio.

How long it takes, by who is listening

Nobody spends a day in a classroom. Every module exists in three lengths; a person takes the length their role needs, and every length ends with the same recorded questionnaire, so the training record is complete either way.

Briefing1 h10 min a module, for executives, sales and anyone who must know the rules, not run them
Standard2 h 30 min25 min a module, for regulatory, quality and business-development staff
Expanded5 h50 min a module, for technical staff who run the procedure day to day
Who takes this courseLengthTotal time
Business development and export salesBriefing1 h
Finance, pricing and tendersBriefing1 h

Letter of credit course outline: 6 modules

6 modules. Under each title are the three things the listener can do afterwards; the audio itself runs 10 to 50 minutes depending on the length chosen.

  1. 1Apply the Late Payment Directive to your European invoices

    • The contract sentence that makes a ninety-day request a written exception to the sixty-day limit.
    • How to calculate statutory interest on an overdue invoice, which runs without a reminder first.
    • Why one payment-terms template for all of Europe slows the deals in markets with different habits.
  2. 2Match Incoterms 2020 and payment milestones to each supply agreement

    • Which Incoterms 2020 rule passes transit risk to the buyer at a point you can prove with paperwork.
    • How to tie each payment milestone to an event the buyer cannot dispute, such as signed delivery.
    • When open account is fine and when payment against documents keeps the goods yours until money moves.
  3. 3Structure Letters of Credit to the Uniform Customs and Practice, UCP 600

    • What to check in a draft Letter of Credit before you accept it, while the bank will still amend it.
    • How to spot the mismatch in a name, date or description that lets a bank refuse your documents.
    • Why your export team reads the credit terms before sales signs, and what it looks for first.
  4. 4Choose a trade credit insurance policy that covers your real market risks

    • How to compare two credit insurance quotes on the limits that decide whether a claim gets paid.
    • The difference between commercial and political risk cover, and which one your buyer's country needs.
    • What to put in the application so the insurer's assessment of your buyers comes back fast.
  5. 5Recover overdue European payments through local legal and mediation routes

    • How to escalate an overdue invoice in steps that keep the distributor ordering from you.
    • How the European Payment Order lets you pursue an unpaid, uncontested invoice without a full trial.
    • When mediation under Directive 2008/52/EC or arbitration beats a lawsuit in the buyer's home court.
  6. 6Build a credit strategy that puts sales and finance on the same page

    • How to build a customer checklist that flags a risky distributor before the first order ships.
    • The one-page handoff that tells finance what sales promised before the contract is signed.
    • Why a scheduled review of payment policy catches a slow-paying buyer before cash flow notices.
The founders

One of us was inspected. The other one pays for the training.

Every claim below is sourced on the about page: the medicines register, the Lithuanian Pharmaceutical Union board list, the university directory.

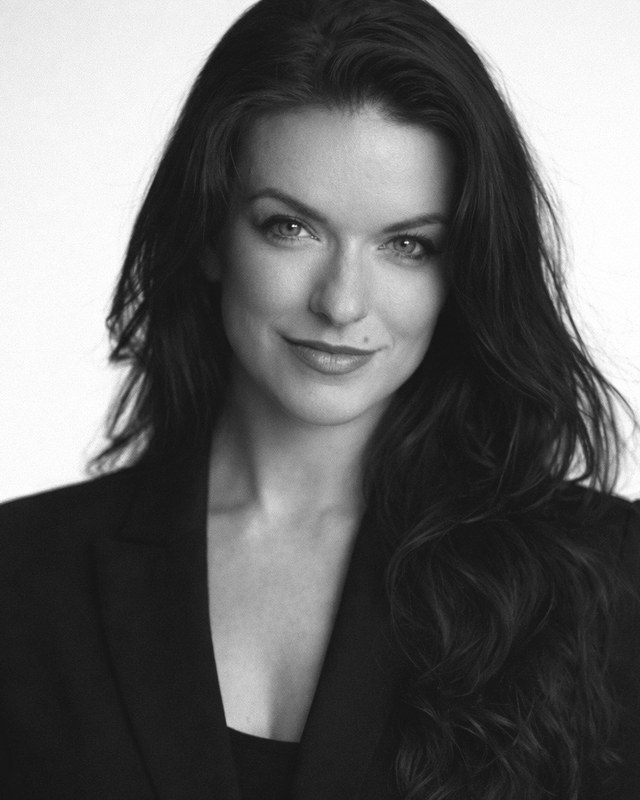
Justina Krukonytė-Racz

Justina Krukonytė-Racz

Co-founder. Licensed pharmacist.

GDPResponsible PersonWarehouse & logistics

Licensed pharmacist. Responsible Person at Tamro (PHOENIX group), where she led the GDP set-up of the distribution centre.

The Responsible Person is the named person the regulator holds accountable for every pallet that leaves the building.

She writes the modules around the procedures a GDP inspection checks. Board member of Lithuanian Pharmaceutical Union.

Listed in the Lithuanian medicines register as Pharmacist.

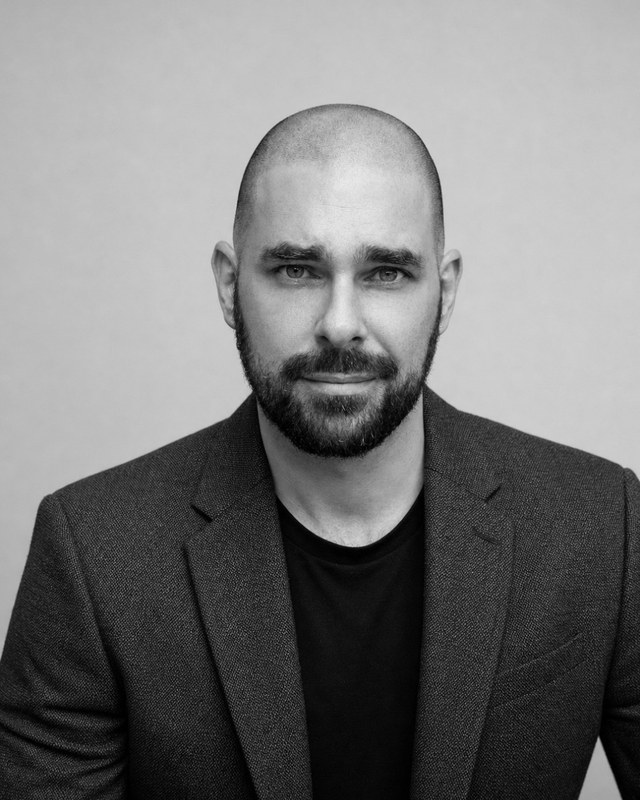
Prof. Ben Racz

Prof. Ben Racz

Co-founder. Builds the platform and is responsible for delivery, records and pricing.

Platform & deliveryQuantitative researchCarnegie Mellon

He was Professor of the Practice at the College of Engineering at Carnegie Mellon University, where he taught Advanced Quantitative Finance and Algorithmic Trading to MSc students.

He is the founder and Managing Director of Algorithmic Sciences, a scientific research and consulting firm. Earlier he co-founded a data-driven growth consultancy, a data-science based wholesale trading company and an information security firm.

More about Ben at benracz.com

Questions about letter of credit training

Why are letter of credit payments refused?

Under UCP 600 banks pay only against documents that comply on their face with the credit's terms, so small discrepancies, such as a date, a description that does not match, a missing signature or a late presentation, can lead the bank to refuse. Banks have up to five banking days after presentation to examine the documents. This course shows exporters how to check documents before they reach the bank.

What is a confirmed letter of credit?

A confirmed letter of credit carries a second promise to pay, added by a confirming bank, often in the exporter's own country, on top of the promise of the buyer's bank. The exporter is then protected if the issuing bank or its country cannot pay. Confirmation costs a fee, so it is mostly worth it for new buyers or banks in markets with higher risk.

Is there a certificate?

Yes. Every learner who finishes the course receives a certificate in their own name, and every module ends with a recorded multiple-choice questionnaire, so the certificate sits on top of a per-person training record. The certificate documents in-company training; it is not a professional qualification or an accreditation, and your quality or human-resources manager sets the pass mark and decides when a module is retaken.

How long does the course take?

6 modules, each in three lengths: a 10-minute briefing, a 25-minute standard run and a 50-minute expanded walk-through. The whole course takes 1 h in the briefing length and 5 h in the expanded length. People take the length their role needs, and every length ends with the same recorded questionnaire, so the training record is complete either way.

Who should take this course?

It is written for Finance, sales. Owners, managers and sales staff hear the briefing length, regulatory, quality and business-development staff take the standard run, and the people who run the procedure every day get the expanded version. One licence covers one named person on this course for a year, so the same title can be rolled out across a whole team at once.

Is this training accepted as a GMP training record by an auditor?

EU GMP Chapter 2 and 21 CFR 211.25 require documented, effective training, and that is what the course produces: a recorded multiple-choice result per module and per person, a certificate per learner and a transcript of what was taught. No provider can promise acceptance by a specific inspector; the record is built to answer what inspectors ask for, and your quality manager decides the pass mark.

How is it delivered and how fast?

The course arrives as audio files with a companion workbook, a full transcript and the questionnaire per module, within 72 hours of your payment arriving. You host the files on your own system or share them as you like; there is no platform to log into and no learner management system to set up. The free sample module arrives on request, before any purchase.

What does it cost per learner?

The list price is 9 euros per module, per learner, per year, so this course is 54 euros for one person for twelve months. The price per learner falls as more people take the same course: 10 learners pay 10 percent less and the discount keeps growing to 50 percent at 1000 learners. Type a number on the price panel and the yearly total appears.

Get this course for your team

One licence is one person on this course for a year. All three lengths, the workbook, the certificate and the training record are included in every purchase. Pick how many people, add it to the cart, and you have an invoice in your inbox.

Free sample module

Hear one full module before you spend a cent. Send your company and the role you want trained, and a complete sample module comes back with its workbook and transcript.

Connect on WhatsApp

or email [email protected], or ask for a written quote for your team